Mortgage Escrow Account Explained for Homeowners
Mortgage escrow account explained for homeowners: learn how escrow works, why payments change, and how to spot errors before they cost you.
By Georgia Poulle
Your monthly mortgage payment is not just principal and interest. For many homeowners, a significant chunk of that payment goes into an escrow account, a financial holding tank that your lender uses to pay property taxes and homeowners insurance on your behalf. If you have ever noticed your payment jump by a few hundred dollars or received a check for an overage you did not expect, escrow is likely the reason. Understanding how this account works is essential for budgeting and avoiding unpleasant surprises.
Escrow accounts are standard on most mortgages, especially if you put down less than 20 percent, but they are also a frequent source of confusion. Homeowners often wonder why the payment changes, how the lender calculates the amount, and what happens if the account runs short. This mortgage escrow account explained for homeowners will walk you through the mechanics, the math, and the steps you can take to keep your escrow on track.
What an Escrow Account Is and What It Covers
An escrow account is a trust account your mortgage servicer establishes to hold money for specific property-related expenses. Instead of sending you a bill for property taxes and insurance each year, your servicer collects a portion of those costs with every monthly payment and holds the funds until the bills come due. When the tax bill arrives, the servicer pays it from escrow. When the insurance premium is due, the servicer pays that too. This arrangement protects both you and the lender: you avoid large lump-sum bills, and the lender ensures the property remains insured and tax liens do not jeopardize its collateral.
The expenses covered by escrow are typically limited to those that protect the lender's interest in the property. The most common items are property taxes (county, municipal, and school taxes) and homeowners insurance (hazard insurance). In some cases, escrow may also cover mortgage insurance premiums, flood insurance, or other required assessments. Condominium association dues are rarely escrowed, though some lenders may allow it. The key distinction is that escrow does not cover utilities, maintenance, or any expense that is not tied to the property's tax and insurance obligations.
Escrow is not a fee or a separate charge. It is simply a way to budget for expenses you would otherwise pay directly. The money in escrow belongs to you; it is held in trust and must be used for the designated bills. Lenders are required by law to provide an annual escrow statement that shows how much was collected, how much was paid out, and how the account balance compares to the target minimum.
How Escrow Is Funded Through Your Monthly Payment
Your monthly mortgage payment consists of four components, often abbreviated as PITI: principal, interest, taxes, and insurance. The principal and interest portion goes toward repaying the loan itself. The taxes and insurance portion is deposited into your escrow account. When you see a mortgage payment quote, it usually includes an estimate of these escrow amounts, even though they are not part of the loan repayment.
To calculate your escrow payment, your servicer first estimates the total annual cost of your property taxes and insurance. That total is divided by 12 to determine the monthly escrow portion. However, the servicer must also maintain a cushion, typically equal to two months of escrow payments, to ensure there is enough money on hand to pay bills before the next collection cycle. This cushion is built into your monthly payment, which is why the initial escrow deposit at closing often equals several months of taxes and insurance.
For example, suppose your annual property taxes are $4,800 and your homeowners insurance is $1,200. The total annual escrow expense is $6,000, or $500 per month. If your servicer requires a two-month cushion, your monthly escrow payment might be set slightly higher (for instance, $540) to gradually build that cushion. At closing, you may be required to deposit enough to cover the cushion plus any taxes due before the first payment. This is why closing costs often include an escrow prepayment.
The important takeaway is that your escrow payment is not fixed for the life of the loan. It is recalculated annually based on actual tax and insurance costs, which can rise or fall. This is the primary reason your total mortgage payment can change even if your interest rate is fixed.
Why Escrow Payments Fluctuate Annually
Escrow payments change because property taxes and insurance premiums change. Local governments reassess property values and adjust tax rates, and insurance companies raise premiums to cover rising repair costs or catastrophic risks. When your servicer receives new tax and insurance bills, it performs an escrow analysis to determine whether your current monthly payment is sufficient to cover the upcoming year's expenses.
If the analysis shows a shortage, meaning your escrow balance is projected to fall below the required cushion, your servicer will adjust your monthly payment upward. If there is a surplus, you may receive a refund check or a credit toward future payments. The analysis also accounts for any changes in the cushion requirement. The result is a new escrow payment that spreads the higher (or lower) costs over the next 12 months, plus any amount needed to make up a shortage.
Homeowners are often surprised by how much the payment can jump. A $600 annual increase in property taxes translates to a $50 monthly increase, but if the servicer also needs to recover a shortage from the previous year, the increase can be double that amount. For example, if your escrow account was short by $600 because taxes rose unexpectedly, the servicer may spread that shortage over 12 months, adding another $50 per month. The combined effect is a $100 monthly increase, which can strain a budget.
To prepare for these fluctuations, review your escrow statement carefully each year. The statement shows the projected tax and insurance costs, the cushion requirement, and how your payment was calculated. If you anticipate a large increase, you can adjust your budget or consider paying the shortage in a lump sum to reduce the monthly impact. Some servicers allow this; others may require it if the shortage is large.
How to Review Your Escrow Statement and Resolve Errors
Your servicer must provide an annual escrow account statement, typically within 30 days of the escrow analysis. This statement is a valuable tool for verifying that your escrow is being managed correctly. It shows the beginning balance, deposits, payments, ending balance, and the projected activity for the coming year. It also discloses the cushion requirement and any surplus or shortage.
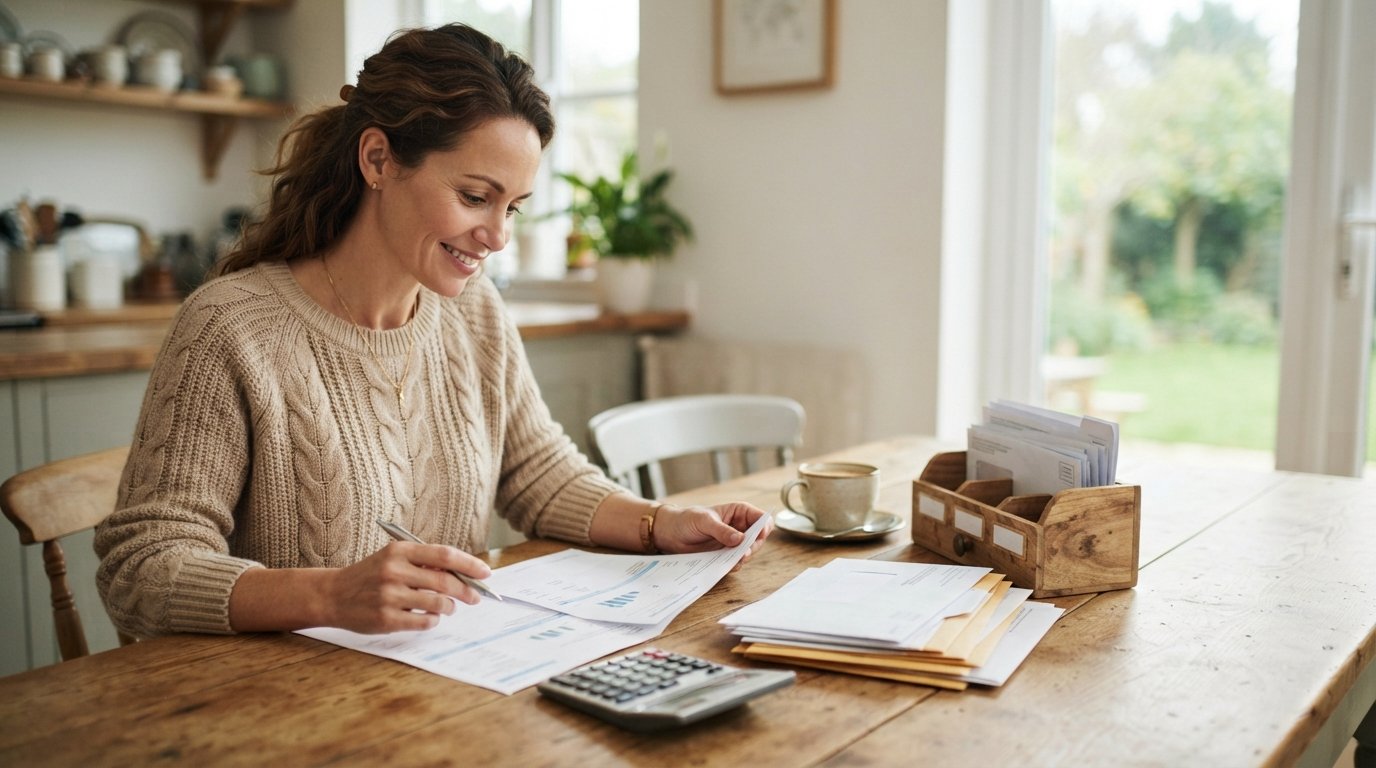
Reviewing the statement is straightforward if you follow a few steps. First, compare the tax and insurance amounts listed on the statement to the actual bills you received from your tax authority and insurance company. Errors can occur if the servicer uses outdated information or pays the wrong amount. Second, check the math: the monthly escrow payment should equal one-twelfth of the total annual expenses plus the cushion adjustment. Third, confirm that the payments were made on time and to the correct recipient. If you find a discrepancy, contact your servicer immediately and provide copies of the correct bills.
Common escrow errors include paying taxes to the wrong taxing authority, failing to apply a homestead exemption, or using an incorrect insurance premium. In some cases, the servicer may have paid a bill late, resulting in penalties. You have the right to request a corrected escrow analysis and, if necessary, to file a complaint with the Consumer Financial Protection Bureau. Resolving errors promptly can prevent unnecessary payment increases and protect your credit.
If your escrow account is short because of a servicer error, you should not have to pay the shortage. The servicer must correct the account and may be required to refund any overage. If the shortage is legitimate (for example, taxes genuinely increased), you can still ask to spread the repayment over a longer period, though the servicer is not obligated to agree. The key is to act quickly and keep detailed records of all communications.
For homeowners who want to compare loan options or understand how different mortgage products handle escrow, platforms like MortgageDirectory offer plain-language guides and a payment calculator that can help you estimate total monthly costs, including escrow. Understanding the full picture before you choose a lender can save you from surprises later.
Managing Escrow Shortages and Surpluses
Escrow shortages are common and can be managed. When you receive an escrow analysis showing a shortage, you have two main options: pay the shortage in a lump sum or allow the servicer to spread it over the next 12 months. Paying in a lump sum reduces your monthly payment increase, but it requires cash on hand. Spreading the shortage increases your monthly payment temporarily, but it avoids a large out-of-pocket expense. Choose the option that fits your budget and cash flow.
Surpluses, on the other hand, occur when your escrow account has more money than required. If the surplus is less than $50, the servicer may credit it to your account. If it is $50 or more, the servicer must refund it to you within 30 days. You can also choose to apply the surplus to future escrow payments, which lowers your monthly payment slightly. Do not ignore a surplus check; it is your money and can be used for other financial goals.
One strategy to avoid large shortages is to monitor your property tax and insurance costs proactively. If you receive a notice of a tax increase or an insurance renewal with a higher premium, contact your servicer to see if an escrow adjustment is warranted. Some servicers will adjust the escrow payment mid-year if they receive updated bills. Keeping your servicer informed can help smooth out payment changes.
Escrow and Your Rights as a Homeowner
Federal law, specifically the Real Estate Settlement Procedures Act (RESPA), governs how servicers must manage escrow accounts. Under RESPA, servicers must provide an annual escrow statement, conduct an escrow analysis at least once a year, and maintain a cushion of no more than one-sixth of the total annual escrow payments (which equals two months). Servicers must also respond to escrow-related inquiries within a reasonable time and correct errors promptly.
If you believe your servicer has violated escrow rules, you can file a complaint with the CFPB or your state's attorney general. Common violations include failing to conduct an annual analysis, miscalculating the cushion, or not refunding surpluses. Knowing your rights empowers you to hold your servicer accountable and ensure your escrow is managed fairly.
Finally, remember that escrow is not mandatory for all loans. If you have at least 20 percent equity in your home, you may be able to cancel escrow and pay taxes and insurance directly. This gives you more control over your money but requires disciplined budgeting. Weigh the pros and cons carefully, and consider whether the convenience of escrow outweighs the potential for payment fluctuations.
Understanding your escrow account is a key part of homeownership. By reviewing your statements, preparing for annual adjustments, and knowing your rights, you can keep your escrow on track and avoid financial surprises. For more tools and resources to compare mortgage rates and estimate payments, visit RateChecker.com and explore personalized rate options for your situation.