Property Tax Assessment vs Appraisal: Key Differences
Understand the property tax assessment vs appraisal difference and how each valuation affects your tax bill and mortgage options.
By Georgia Poulle
Your home's value affects two very different parts of your financial life: the property taxes you pay to your local government and the mortgage terms you qualify for with a lender. Many homeowners assume these two numbers are the same, or that one automatically drives the other. That assumption leads to confusion, surprise tax bills, and missed opportunities to lower costs. The property tax assessment vs appraisal difference matters because each valuation serves a distinct purpose, follows its own rules, and can produce significantly different dollar figures for the exact same house.
Understanding who performs each valuation, what standard they use, and how you can challenge or leverage the result puts you in a stronger position as a homeowner. Whether you are buying your first home, refinancing an existing mortgage, or simply reviewing your annual tax bill, knowing how these valuations interact helps you spot errors, plan your budget, and make smarter borrowing decisions.
What Is a Property Tax Assessment?
A property tax assessment is a value assigned to your home by your local county or municipal tax assessor. This figure becomes the basis for calculating your annual property tax bill. The assessor multiplies the assessed value by the local tax rate (often called a millage rate) to determine what you owe. Assessment offices typically review properties on a set cycle, which can range from every year to every five years depending on your jurisdiction.
Assessors do not inspect every home individually each cycle. Instead, they rely on mass appraisal techniques: statistical models, recent sales data in your neighborhood, property characteristics, and sometimes exterior drive-by reviews. This approach keeps costs down for the municipality but means the assessed value is a broad estimate rather than a precise, room-by-room evaluation. It also means assessed values can lag behind rapid market shifts, which works in your favor when prices are rising fast and against you when they fall.
The assessed value is not always the same as your home's market value. Many jurisdictions apply an assessment ratio, meaning they tax only a percentage of the full market value. For example, if your home is worth $400,000 and your county uses a 70 percent assessment ratio, your assessed value for tax purposes is $280,000. Always check your local rules to understand how your assessment was derived.
Why Assessments Exist
Local governments need a predictable revenue stream to fund schools, roads, emergency services, and public infrastructure. Property taxes provide that stability. The assessment process distributes the tax burden across all property owners based on relative value. If your assessment is higher than your neighbor's for a comparable home, you pay more, which is why accuracy and fairness matter.
How to Challenge an Assessment
If you believe your assessed value is too high, most jurisdictions offer a formal appeal process. You typically have a narrow window after receiving your assessment notice to file. Gather recent comparable sales, a professional appraisal if you have one, and photos documenting any condition issues the assessor may have missed. A successful appeal can lower your tax bill for years, so it is worth the effort when the numbers clearly do not add up.
What Is an Appraisal?
An appraisal is an independent, professional opinion of your home's market value, typically ordered by a lender during a purchase or refinance transaction. Licensed or certified appraisers inspect the property, measure square footage, note upgrades and condition, and compare it to recent sales of similar homes in the area. The result is a detailed report that lenders use to confirm the home is worth at least as much as the loan amount.
Appraisals follow the Uniform Standards of Professional Appraisal Practice (USPAP), which sets strict ethical and methodological guidelines. The appraiser's conclusion, called the appraised value, reflects what a willing buyer would likely pay a willing seller in an open market. Because appraisals are tied to a specific loan transaction, they are point-in-time snapshots, usually valid for a few months.
The appraisal protects both the lender and the borrower. For the lender, it reduces the risk of lending more than the collateral is worth. For the borrower, it prevents overpaying for a property. If the appraisal comes in lower than the purchase price, the buyer may need to renegotiate, bring more cash to closing, or walk away.
When Appraisals Are Required
Appraisals are almost always required for mortgage purchases and most refinances. Some streamlined refinance programs waive them for well-qualified borrowers, but the lender still needs a reliable value estimate. Home equity loans and lines of credit may also require an appraisal, depending on the loan-to-value ratio and the lender's policies.
Appraisal vs. Home Inspection
An appraisal is not a home inspection. The appraiser focuses on value, not on whether the furnace works or the roof leaks. A home inspection is for the buyer's benefit and covers the physical condition of the property. Both are important, but they serve entirely different purposes in the transaction.
The Core Property Tax Assessment vs Appraisal Difference
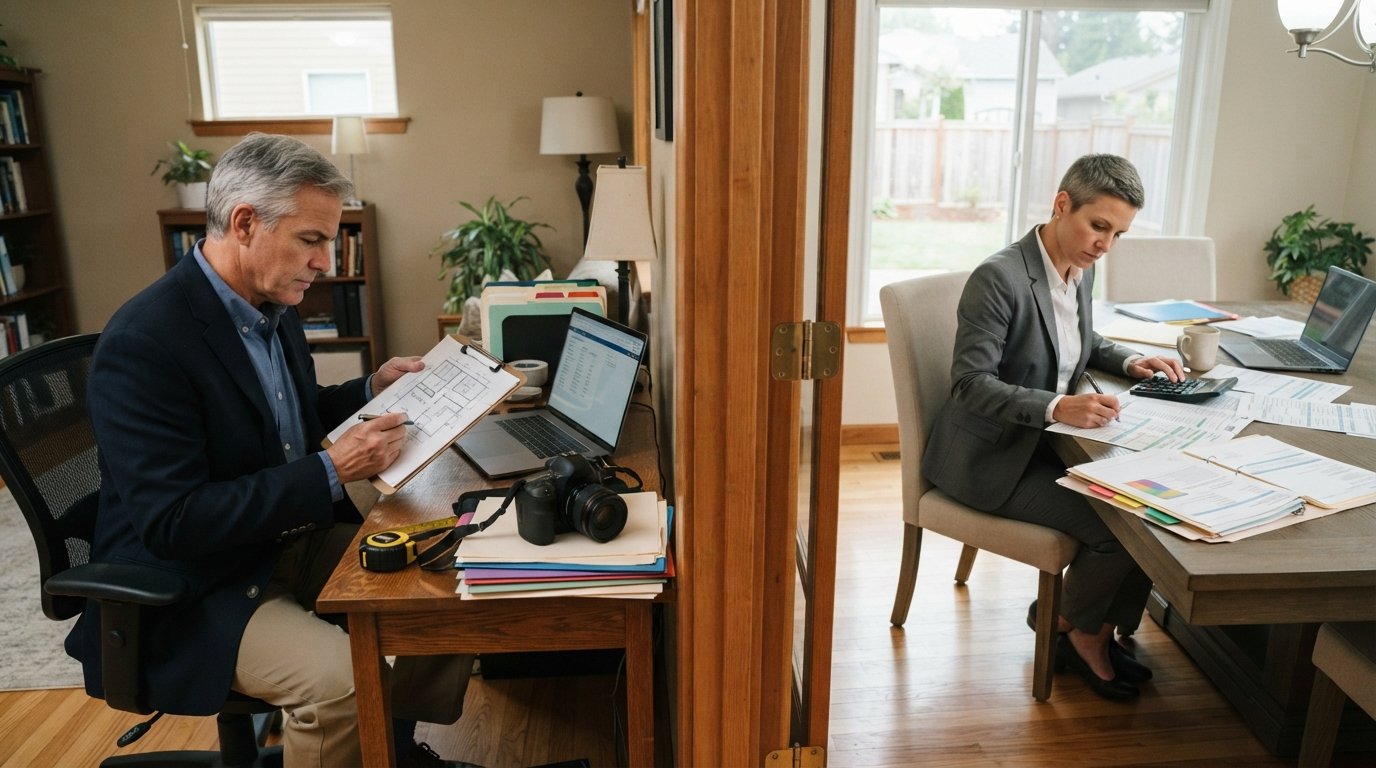
The central difference between a property tax assessment and an appraisal comes down to purpose, authority, and methodology. An assessment exists to fund local government services and is performed by a government employee or contractor using mass appraisal techniques. An appraisal exists to support a mortgage or property transaction and is performed by an independent licensed professional using individual, evidence-based analysis.
Another critical distinction is who controls the outcome. You can appeal an assessment through a formal government process. You generally cannot appeal an appraisal directly, though you can request a reconsideration or a second appraisal through your lender if you have strong evidence the value is wrong. The table below summarizes the key contrasts.
- Purpose: Assessment determines property taxes; appraisal determines lending value and market price validation.
- Who performs it: Assessment by a county or municipal assessor; appraisal by a licensed independent appraiser.
- Method: Assessment uses mass appraisal and statistical models; appraisal uses individual inspection and comparable sales analysis.
- Frequency: Assessment follows a local cycle (often annual to five years); appraisal happens per transaction.
- Appeal rights: Assessment can be formally appealed; appraisal can be challenged only through limited lender channels.
Because these valuations serve different masters, they often diverge. A hot market might push appraised values up quickly while assessments lag by a year or more. Conversely, a declining neighborhood might see appraisals drop immediately while assessments stay high until the next revaluation cycle. Recognizing this lag effect helps you anticipate changes in your tax bill and your home equity position.
For homeowners planning their broader housing costs, it helps to see how property taxes fit alongside insurance and mortgage payments. Our guide on property taxes and homeowners insurance costs explains how these expenses combine and what you can do to manage them.
How Each Valuation Affects Your Finances
Your property tax assessment directly determines your annual tax bill. If the assessed value rises, your taxes rise, unless the tax rate drops to compensate. Many homeowners are surprised when their tax bill increases even though they did not make improvements or see a dramatic market jump. The reason is often a reassessment cycle catching up to market conditions or a local budget increase that raises the tax rate.
Your appraisal affects your mortgage approval, your loan-to-value ratio, and your ability to refinance or tap equity. A higher appraisal gives you more borrowing power and may eliminate the need for private mortgage insurance if your loan-to-value ratio drops below 80 percent. A lower appraisal can block a refinance, force you to bring more cash, or reduce the amount you can borrow through a home equity line of credit.
Both valuations also influence your overall financial planning. Property taxes are an ongoing, predictable expense that you can estimate and budget for. Appraisals are episodic, tied to major transactions. Understanding when each one changes and why helps you avoid surprises and time your decisions strategically.
Real-World Example
Suppose you buy a home for $450,000. The appraisal confirms the value at $450,000, and your lender approves the mortgage. Six months later, your county reassesses the property at $470,000 based on neighborhood sales, raising your tax bill by several hundred dollars. Your appraisal is still $450,000 and will not change unless you refinance or sell. This gap is normal and illustrates why the two numbers should never be treated as interchangeable.
How to Use Both Valuations to Your Advantage
Smart homeowners treat assessments and appraisals as tools rather than nuisances. Start by reviewing your assessment notice each year. Compare the assessed value to recent sales in your area and to your own home's condition. If something looks off, file an appeal within the deadline. Even a modest reduction in assessed value can save you hundreds of dollars annually.
When you are considering a refinance or home equity loan, order a copy of your most recent appraisal if you have one, and check whether your lender offers an appraisal waiver. If you have made significant improvements, document them before the appraisal so the appraiser can account for the added value. A well-prepared home often appraises higher, which can improve your loan terms.
If you are shopping for a mortgage or refinance, comparing real-time rates from multiple lenders is one of the most effective ways to lower your long-term costs. Platforms like LoanFinancing provide educational resources and calculators that help you estimate payments and understand how loan terms interact with your home's value. Combining that knowledge with a clear grasp of your assessment and appraisal positions you to make confident, cost-effective decisions.
Step-by-Step: Reviewing Your Valuations
- Locate your most recent property tax assessment notice and your latest appraisal report.
- Compare each value to recent comparable sales in your neighborhood.
- Identify any discrepancies, such as incorrect square footage or missed improvements.
- If the assessment is too high, file an appeal before the deadline with supporting evidence.
- If you plan to refinance, share your improvement documentation with the appraiser in advance.
Following these steps keeps both valuations accurate and aligned with your financial goals. It also gives you a paper trail if you need to challenge either number later.
Common Myths and Mistakes
One persistent myth is that a higher appraisal automatically means higher property taxes. In reality, assessments and appraisals are separate processes, and an appraisal does not trigger a reassessment. Another myth is that you can use your appraisal to appeal your assessment. While an appraisal can be supporting evidence, the appeal process follows local rules and may require specific forms or comparable data.
A frequent mistake is ignoring the assessment notice until the tax bill arrives. By then, the appeal window may have closed. Another mistake is assuming the assessed value is always lower than market value. In some jurisdictions, assessments can exceed market value, especially after a rapid price surge followed by a slowdown. Staying informed and acting early prevents these pitfalls.
Finally, some homeowners confuse the appraisal with the market value estimate they see on consumer real estate websites. Automated valuation models (AVMs) are not appraisals and are not accepted by lenders for mortgage decisions. They can be useful for a quick sanity check, but they should never replace a professional appraisal or a formal assessment review.
Final Thoughts
The property tax assessment vs appraisal difference is not just a technicality; it is a practical distinction that affects your tax bill, your borrowing power, and your overall financial strategy. Assessments are government valuations for taxation, driven by mass appraisal and subject to appeal. Appraisals are independent, transaction-driven valuations used by lenders to confirm market value. Knowing how each works, when to challenge them, and how to use them to your advantage puts you in control of your housing costs. Review your numbers regularly, keep good records, and compare mortgage options carefully so that both valuations work in your favor.