Mortgage Appraisal Process Explained for Homebuyers
Understand the mortgage appraisal process explained for homebuyers, from scheduling to low-value outcomes, and protect your budget at closing.
By Daniel Reed
You found the house. Your offer was accepted. You are already picturing where the couch goes. Then your lender says four words that can feel like a cold splash of water: we need an appraisal. For many homebuyers, the appraisal is the most mysterious step in the mortgage journey. It is not a home inspection, it is not a negotiation tactic, and it is not something you can simply skip. It is a professional, independent valuation that protects both you and your lender from paying more than a property is worth. Understanding how it works, what it costs, and what happens when the number comes back low can save you thousands of dollars and a mountain of stress. This guide walks through the entire mortgage appraisal process explained for homebuyers, from scheduling to final review, so you know exactly what to expect at every stage.
What a Mortgage Appraisal Actually Is (And Why Lenders Require It)
A mortgage appraisal is an unbiased, written estimate of a property's fair market value, prepared by a state-licensed or certified appraiser. Lenders require it because the home serves as collateral for the loan. If a borrower defaults, the lender needs reasonable confidence that the property can be sold for at least the amount of the loan. Without an appraisal, a lender would essentially be guessing, and that is not a risk most financial institutions are willing to take on a 15 or 30 year commitment.
It helps to separate the appraisal from two other evaluations buyers often confuse it with. A home inspection examines the physical condition of the property, things like the roof, plumbing, electrical systems, and structural integrity. An appraisal, by contrast, focuses on value. It may note obvious condition issues, but its purpose is to answer one question: what would a willing buyer pay a willing seller for this home in the current market? A third term, the assessed value, comes from your local tax authority and is used for property tax purposes. Assessed value and appraised value frequently differ, sometimes by a wide margin, because they serve completely different functions. If you want a deeper walkthrough of these distinctions alongside other common buyer questions, our guide on new purchase mortgage FAQs explained covers the topics that tend to trip up first-time buyers.
Appraisals are almost always required for conventional loans, FHA loans, VA loans, and USDA loans. In rare cases, a lender may waive the appraisal through a property inspection waiver program, but this typically happens only when the loan-to-value ratio is low and the borrower has strong credit. For the vast majority of homebuyers, budgeting for an appraisal is simply part of the cost of getting a mortgage.
How the Appraisal Process Unfolds, Step by Step
Once you are under contract and your lender orders the appraisal, the process generally follows a predictable sequence. Timelines vary by market, but most appraisals are completed within one to three weeks from the date they are ordered. Here is how the steps typically break down.
- Your lender orders the appraisal. After your loan application is submitted, the lender places the order through an appraisal management company or directly with an appraiser. Federal rules require that the appraiser remain independent, meaning your lender cannot handpick someone likely to inflate the value.
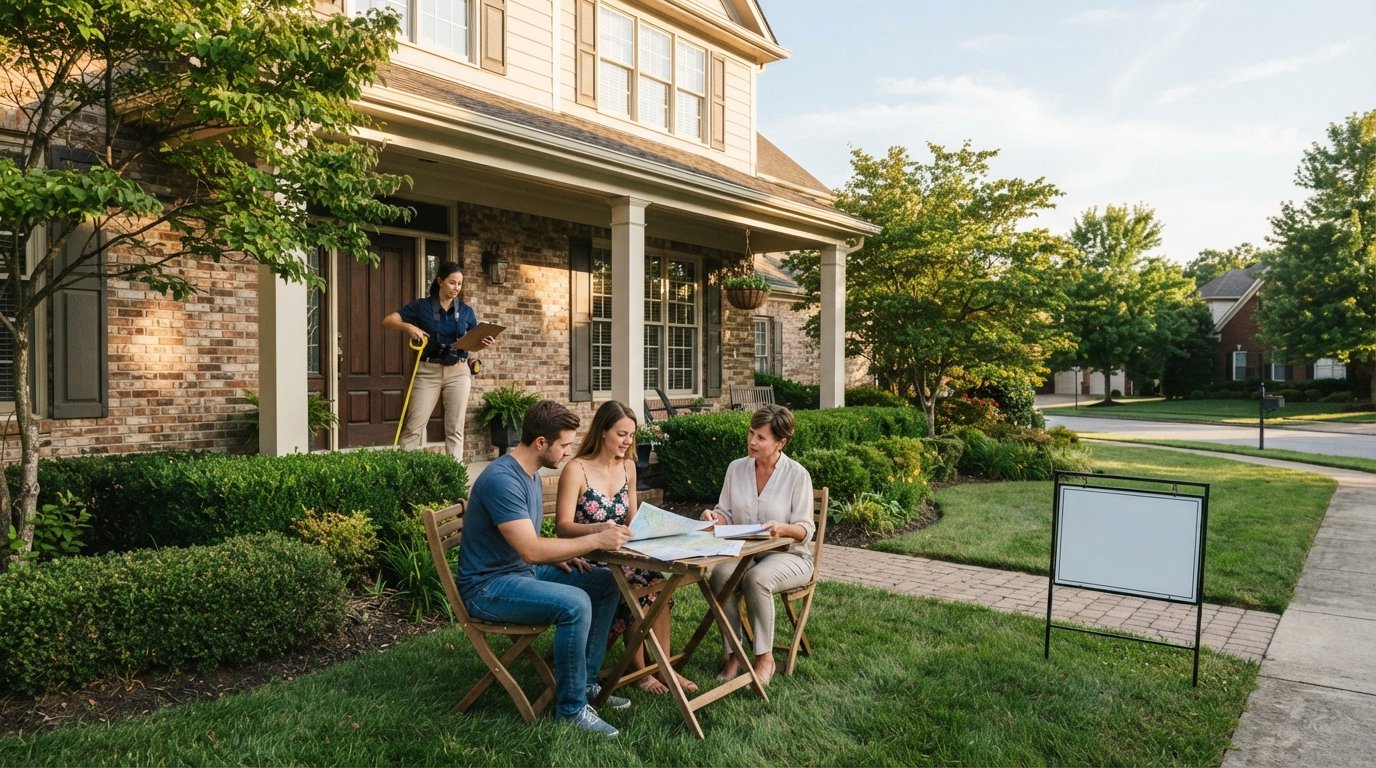
- The appraiser schedules a property visit. You or your real estate agent will coordinate access. The appraiser walks through the home, measures square footage, notes the number of bedrooms and bathrooms, checks the condition of major systems, and takes photographs.
- The appraiser researches comparable sales. Back at the office, the appraiser pulls recent sales of similar homes in the same neighborhood or nearby, known as comparables or comps. Adjustments are made for differences in size, age, lot, upgrades, and location.
- The appraisal report is delivered. The final report includes the appraised value, the comparable sales used, photographs, a neighborhood analysis, and any notes about conditions that affect value.
- Your lender reviews the report. The underwriting team confirms the value supports the loan amount. If everything aligns, your loan moves forward.
The cost of an appraisal is usually between $300 and $700 for a standard single-family home, though complex properties, large acreage, or high-cost markets can push that figure higher. You typically pay for the appraisal upfront or as part of your closing costs. Importantly, the appraisal fee is generally non-refundable even if the loan does not close, because the appraiser has already performed the work.
What Appraisers Look For During the Property Visit
Many buyers assume the appraiser is hunting for reasons to lower the value. In reality, the appraiser is documenting facts. The visit usually takes between 30 minutes and an hour, and the appraiser is not there to critique your decorating choices or tell you whether the kitchen needs updating. The goal is to gather enough data to support a defensible value opinion.
Key factors that influence the final number include the home's gross living area, the number of bedrooms and bathrooms, the age and overall condition, recent updates or renovations, lot size and location, and the quality of the surrounding neighborhood. The appraiser will also note anything that could affect marketability, such as a busy road, an unusual floor plan, or deferred maintenance. Here are the items that most consistently move the needle on value.
- Square footage and functional layout, including whether the flow of rooms makes sense for typical buyers
- Recent sales of comparable homes, ideally closed within the last three to six months and within one mile
- Upgrades that buyers in that market actually pay for, such as updated kitchens or bathrooms
- Condition issues that could require repair, including roof age, HVAC function, and signs of water damage
- External factors like school district, proximity to amenities, and traffic or noise exposure
If you are selling or refinancing, small preparation steps can help, such as tidying the home, making sure the appraiser can access all rooms and the attic or basement, and providing a list of recent improvements with costs. You are not required to do this, but it can help the appraiser understand the property's full story. Remember that the appraiser works for the lender, not for you, and the final value must be supported by market evidence rather than by the seller's asking price.
What Happens When the Appraisal Comes in Low
A low appraisal is one of the most common deal-breakers in real estate, and it can feel deeply unfair when you have already fallen in love with a home. If the appraised value comes in below the purchase price, your lender will base the loan on the lower number. That means you may need to bring more cash to closing to cover the gap, or the seller may need to reduce the price. Neither outcome is automatic, and there are several paths forward.
Your first step is to review the appraisal report carefully with your real estate agent and loan officer. Sometimes the appraiser missed a comparable sale, used an outdated comp, or made a factual error about the home's square footage or features. In those cases, your lender may allow a reconsideration of value, which is a formal request to review specific data points. This is not a guarantee of a higher number, but it is worth pursuing when the report contains clear mistakes. If the value stands, you and the seller can negotiate. The seller might lower the price to the appraised value, you might agree to split the difference, or you might walk away if the contract includes an appraisal contingency.
It is also worth noting that a low appraisal does not necessarily mean you are overpaying. In fast-moving markets, appraisals can lag behind actual sale prices because they rely on closed sales rather than current listings. Still, the lender's risk rules are strict, and the appraised value is the number that counts for financing purposes. If you are comparing loan offers and want to understand how different lenders handle appraisal contingencies, exploring transparent rate and fee comparisons can help you see the full picture before you commit. Platforms like ExpressMortgageQuotes provide educational resources and quote comparison tools for buyers weighing their options, which can be useful when you are trying to understand how a low appraisal might affect your loan terms.
How the Appraisal Fits Into Your Overall Loan Timeline
The appraisal is one piece of a larger underwriting puzzle. It usually happens after you have submitted your full loan application and locked in an interest rate, but before final approval. In a typical purchase transaction, the appraisal is ordered within the first week after your offer is accepted, and the report comes back within two to three weeks. This timing matters because your rate lock, your closing date, and your contingency periods all depend on when the appraisal is completed and reviewed.
If the appraisal is delayed, your closing could be pushed back, which may require extending your rate lock or renegotiating timelines with the seller. To keep things moving, respond quickly to any requests for access, avoid making major financial changes during the process, and stay in close contact with your loan officer. It also helps to understand that the appraiser's opinion is just one data point. Your lender may also review your credit, income, assets, and the title report before issuing a final approval. The appraisal confirms the collateral value, but it does not guarantee that the loan will close.
For buyers using FHA or VA loans, additional appraisal requirements may apply. FHA appraisals include a health and safety review that can flag peeling paint, missing handrails, or other conditions that must be corrected before closing. VA appraisals include a minimum property requirements checklist. These extra steps can add time, so plan accordingly if you are using a government-backed loan.
Appraisal Myths That Cost Buyers Money
Misinformation about appraisals circulates widely, and believing the wrong things can lead to costly decisions. One persistent myth is that the appraiser works for the buyer. In reality, the appraiser is engaged by the lender or an appraisal management company, and the report is delivered to the lender. You typically receive a copy, but you do not control the process. Another myth is that a home inspection can substitute for an appraisal. It cannot. They serve different purposes, and lenders require the appraisal specifically.
A third myth is that you can simply ask the appraiser to raise the value. That is not how it works. Appraisers must support their opinions with market data, and pressuring an appraiser to hit a target number is unethical and, in some cases, illegal. A fourth myth is that the appraised value is the same as the market value. The appraised value is one professional opinion of market value on a given date, and it can differ from what a buyer is willing to pay in a competitive situation. Finally, some buyers believe the appraisal is optional. For most mortgages, it is not. Skipping it would leave the lender without a critical piece of risk information, and your loan would not close.
Practical Tips to Prepare for Your Appraisal
While you cannot control the appraiser's final number, you can make the process smoother. Start by ensuring the appraiser has clear access to the property, including the attic, basement, garage, and any outbuildings. If you have receipts for major improvements, such as a new roof, HVAC system, or kitchen remodel, leave them on the counter with a brief summary. This is not bribery; it is documentation. Appraisers appreciate accurate information about recent upgrades because it helps them justify adjustments to comparable sales.
It also helps to clean and declutter, though the appraiser is not performing a white-glove inspection. The goal is to remove obstacles that could prevent a full evaluation. If you are refinancing, make sure any pets are secured and that the appraiser can move freely through the home. If you are buying, coordinate with your agent so the seller knows when to expect the visit. And always review the final report when you receive it. If something looks wrong, ask questions immediately rather than waiting until closing.
Understanding the mortgage appraisal process explained for homebuyers is ultimately about reducing uncertainty. The more you know about what the appraiser does, how the value is determined, and what your options are if the number comes in low, the better you can protect your budget and your peace of mind. An appraisal is not an obstacle; it is a safeguard that helps ensure you are making a sound financial decision on one of the largest purchases of your life.