How to Compare Mortgage Loan Estimates Side by Side
Master how to compare mortgage loan estimates side by side. Spot junk fees, align key sections, and use RateChecker tools to keep more money in your pocket.
By Daniel Reed
When you are shopping for a mortgage, the offers can start to blur together. One lender quotes a lower rate but higher fees. Another promises no closing costs but a higher rate. A third throws in a discount that disappears in year two. Without a structured method, it is easy to pick the deal that looks cheapest on the surface and miss the one that actually saves you the most. That is where the Loan Estimate comes in. This standardized three-page form, required by federal law, gives you an apples-to-apples view of each offer. But you still need to know how to compare mortgage loan estimates side by side to spot the real differences. This guide walks you through a practical process, from lining up key sections to identifying junk fees, so you can choose with confidence and keep more money in your pocket.
Start With a Side-by-Side Comparison Framework
The first step in how to compare mortgage loan estimates side by side is to create a consistent framework. Gather all your Loan Estimates and place them next to each other, either physically or in a spreadsheet. Because the form follows a standard layout, you can align the same sections across offers. Focus on four main areas: loan terms, projected payments, closing costs, and APR. Each of these tells a different part of the story, and together they reveal the true cost of the loan.
Before you start comparing numbers, make sure each estimate is based on the same loan amount, loan term, and loan type. If one lender quotes a 30-year fixed and another quotes a 5/1 ARM, you are not comparing apples to apples. Ask each lender to provide estimates for the same scenario. Once you have that consistency, you can move through the comparison systematically.
Here is a simple framework to organize your review:
- Loan Terms: Confirm the loan amount, interest rate, monthly principal and interest, and whether there are prepayment penalties or balloon payments.
- Projected Payments: Compare the total monthly payment, including principal, interest, mortgage insurance, and escrow (taxes and insurance).
- Closing Costs: Break down the total closing costs into lender fees and third-party fees, and note which are negotiable.
- APR: Use the Annual Percentage Rate as a summary metric that incorporates both the interest rate and certain fees.
With this framework in place, you can quickly spot which offer is truly the most competitive. But the details matter, so let us dig into each section.
Line Up the Key Sections of the Loan Estimate
The Loan Estimate is designed to make comparison easy, but you need to know where to look. Page 1 gives you the big picture: loan terms, projected payments, and a snapshot of costs. Page 2 breaks down closing costs in detail, and Page 3 provides additional information, including APR and total interest percentage. To compare mortgage loan estimates effectively, align each section across offers.
Loan Terms and Projected Payments
Start with the Loan Terms section on Page 1. Check that the loan amount, interest rate, and monthly principal and interest are clearly stated. Look for any prepayment penalty or balloon payment, which can add risk. Next, move to Projected Payments. This section shows your total monthly payment, including estimated escrow (property taxes and homeowners insurance) and mortgage insurance, if applicable. A lower principal and interest payment might be offset by higher escrow or mortgage insurance, so compare the total monthly payment, not just the loan payment.
Also, note the estimated taxes, insurance, and assessments. These can vary by lender if they use different estimates, so ask for the basis of their figures. If one lender estimates significantly lower taxes, that could be a red flag or a sign they are underestimating your escrow, which could lead to a shortage later.
Closing Cost Details
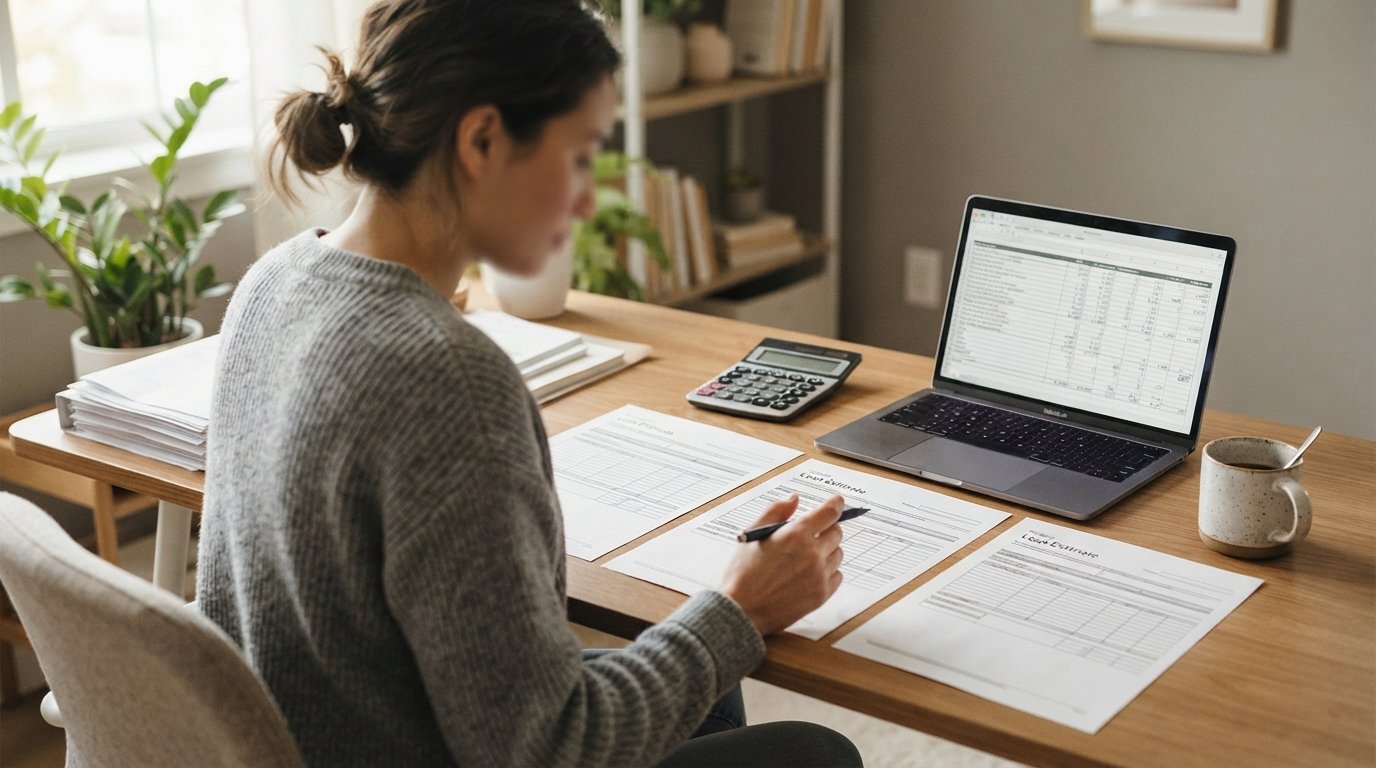
Page 2 of the Loan Estimate is where the real comparison happens. It lists every closing cost, grouped into categories: origination charges, services you cannot shop for, services you can shop for, taxes and other government fees, prepaids, initial escrow payment at closing, and other. To compare mortgage loan estimates side by side, create a spreadsheet with columns for each lender and rows for each fee. Then note the amounts.
Pay special attention to the categories. Origination charges are lender fees, and they are often negotiable. Services you cannot shop for are required by the lender and provided by companies they choose, but you can still compare those fees across lenders. Services you can shop for are exactly that: you can choose your own provider for title, appraisal, and other services, so the lender's estimate is just a placeholder. Taxes and government fees are usually fixed, but verify them. Prepaids include homeowners insurance and prepaid interest, which depend on your closing date. Initial escrow is a cushion for future taxes and insurance, and it can vary slightly among lenders.
APR and Total Interest Percentage
The Annual Percentage Rate (APR) is shown on Page 3, along with the Total Interest Percentage (TIP). The APR is a broad measure of the cost of credit, expressed as a yearly rate. It includes the interest rate plus certain closing costs, such as origination fees and points. Because it standardizes costs, the APR is a useful tool for comparing offers with different fee structures. However, it has limitations: it assumes you keep the loan for its full term, and it may not fully capture costs like prepayment penalties. Use the APR as a starting point, but always dig into the individual fees.
The Total Interest Percentage tells you how much interest you will pay over the life of the loan as a percentage of the loan amount. It is another way to gauge the long-term cost. When comparing estimates, a lower APR and lower TIP generally indicate a cheaper loan, but confirm by looking at the underlying fees.
Compare APR, Points, and Lender Fees Beyond the Interest Rate
The interest rate is just one piece of the puzzle. Two loans can have the same rate but vastly different costs. That is why you need to compare APR, points, and lender fees together. The APR incorporates both the rate and certain fees, giving you a more complete picture. But the APR is not perfect, so use it alongside a detailed fee comparison.
Points are upfront fees paid to the lender to reduce the interest rate. One point equals 1% of the loan amount. If one lender offers a lower rate but charges points, the APR will reflect that trade-off. Compare the APR of each offer, but also calculate the break-even point for points. For example, if you pay $2,000 in points to get a rate that saves you $50 per month, it will take 40 months to break even. If you plan to stay in the home longer than that, points may be worth it. If not, a no-points loan with a slightly higher rate could be better.
Lender fees, often listed as origination charges, include application fees, underwriting fees, and processing fees. These can vary widely. Some lenders advertise low rates but make up for it with high fees. Others charge fewer fees but a higher rate. To compare mortgage loan estimates side by side, add up all lender fees for each offer and compare them directly. Then consider the interest rate and APR together. A loan with a slightly higher rate but much lower fees might be the better deal, especially if you plan to sell or refinance before the loan term ends.
Here is a simple way to evaluate the trade-off between points, fees, and rate:
- List each loan's interest rate, points, and total lender fees.
- Calculate the total cost over your expected holding period (e.g., 5, 7, or 10 years). Include points, fees, and interest payments.
- Compare the total cost for each loan. The lowest total cost for your timeline is likely the best choice.
This approach helps you see beyond the headline rate and make a decision based on your actual plans.
Spot Junk Fees and Negotiable Charges
Not all closing costs are created equal. Some are legitimate and required, while others are inflated or unnecessary. Learning to spot junk fees can save you hundreds or even thousands of dollars. When comparing Loan Estimates, look for fees that seem out of line with industry norms or that are vague. Common junk fees include excessive origination fees, unnecessary administrative fees, and padded third-party services.
Here are some tips to identify and negotiate fees:
- Compare origination charges: These are lender fees and are often negotiable. If one lender's origination fee is significantly higher, ask them to match or lower it.
- Question services you can shop for: The lender estimates costs for title, appraisal, and other services, but you can choose your own providers. Shopping around for these services can lower your costs.
- Watch for duplicate fees: Some lenders may charge separate fees for similar services, such as application and processing. Ask for a breakdown.
- Negotiate: Do not be afraid to ask for a discount or to waive certain fees. Lenders want your business and may be willing to adjust.
Remember that the Loan Estimate is an estimate, not a final number. Some fees can change, but others are subject to tolerance rules. For example, origination charges and fees for services you cannot shop for are subject to a 10% cumulative tolerance, meaning they cannot increase by more than 10% from the estimate to the final Closing Disclosure. This gives you some protection, but you still need to review carefully.
When you compare mortgage loan estimates side by side, flag any fees that seem unusual or that differ significantly from other offers. Ask the lender to explain each fee and whether it is negotiable. A reputable lender will be transparent and willing to work with you.
Use RateChecker Tools to Organize Multiple Quotes
Managing multiple Loan Estimates can be overwhelming, but RateChecker makes it easier. Our platform offers tools to help you compare mortgage rates and organize quotes from multiple lenders. Start by using our rate comparison tool to see personalized quotes from our network of lenders. Then, use our interactive mortgage calculator to estimate monthly payments and see how different rates and fees affect your costs. You can also explore our guides on where to compare mortgage rates online for a smoother shopping experience.
RateChecker is not a lender and does not provide loan offers or approvals. We connect you with participating lenders who can provide personalized quotes. By using our tools, you can gather multiple Loan Estimates and compare them side by side with confidence. For additional resources, visit LoanFinancing for expert guidance on personal loan and mortgage financing.
To streamline your comparison, create a spreadsheet with columns for each lender and rows for each line item from the Loan Estimate. Include the loan terms, projected payments, closing costs, and APR. Then, use the framework outlined above to evaluate each offer. With a systematic approach, you can cut through the noise and find the loan that best fits your financial goals.