How Housing Inventory Affects Mortgage Rates and Home Prices
Housing inventory shapes both mortgage rates and home prices in ways most buyers miss. See how supply trends affect your negotiating power and monthly payment.
By Sasha Demovich
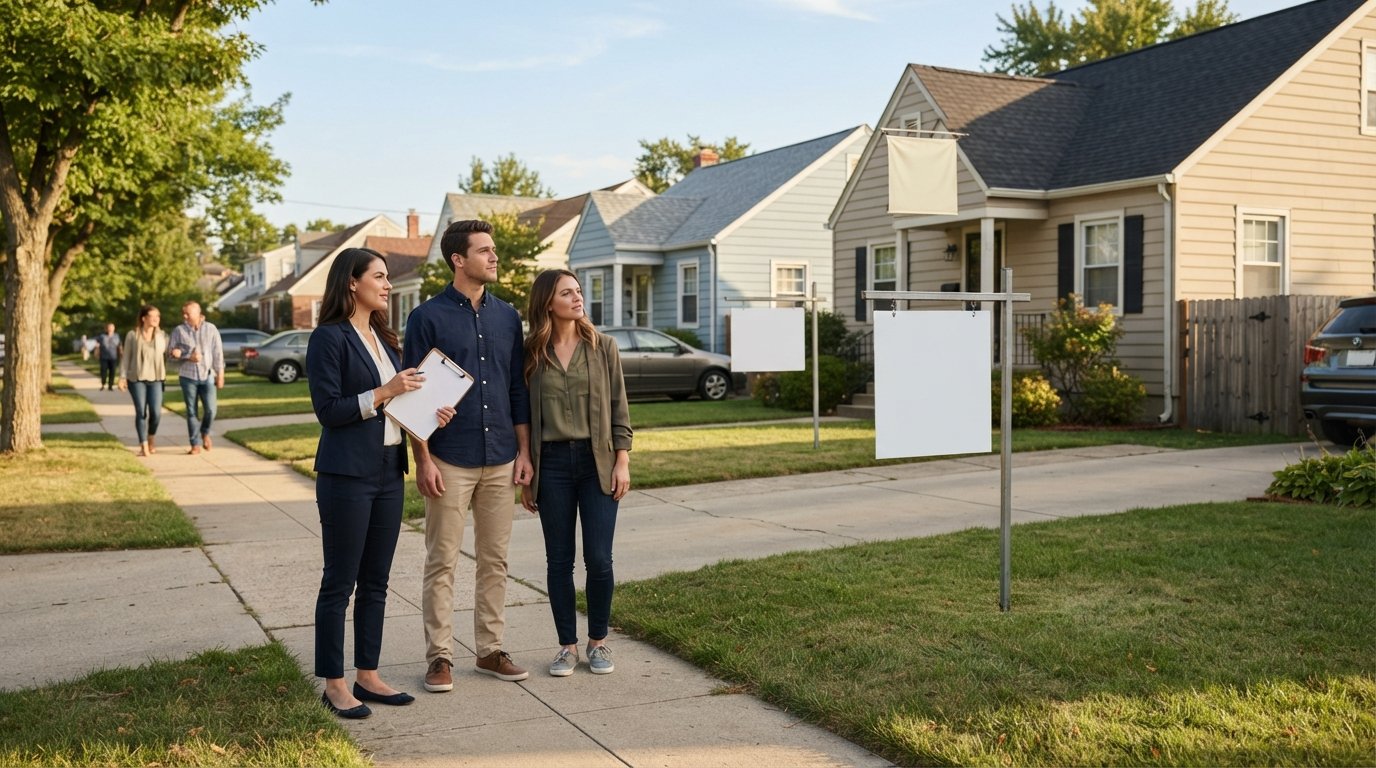
Drive through nearly any American neighborhood and you will notice the same pattern: modest clusters of for-sale signs, a handful of open house banners, and a steady stream of eager buyers circling the same limited listings. That imbalance sits at the center of the most important relationship in residential real estate. The number of homes available for sale, known as housing inventory, shapes everything from how long a property sits on the market to the interest rate a lender quotes you on a thirty-year fixed loan. Understanding this connection is not just academic trivia. It is the difference between overpaying by tens of thousands of dollars and negotiating from a position of strength.
Housing inventory moves in cycles, and those cycles ripple through mortgage pricing, seller psychology, and buyer behavior. When inventory is scarce, competition intensifies, prices climb, and lenders adjust their risk models. When inventory swells, buyers regain leverage, price growth cools, and mortgage rates respond to a different set of economic forces. This article breaks down exactly how housing inventory affects mortgage rates and home prices, why the relationship is not always intuitive, and what you can do as a buyer, seller, or homeowner to make smarter decisions in any market condition.
What Housing Inventory Actually Measures
Housing inventory is typically expressed in two ways: the raw count of active listings in a given market, and the months of supply. Months of supply tells you how long it would take to sell every currently listed home at the present sales pace. A market with three months of supply is considered tight or seller-friendly. A market with six months of supply is balanced. Anything above seven months tilts toward buyers.
Inventory is not a single national number. It varies block by block, city by city, and price tier by price tier. Entry-level homes priced under $300,000 often face chronic shortages, while luxury properties above $1.5 million may sit for months. This stratification matters because mortgage lenders price risk based on the broader economic environment, but buyers and sellers experience inventory conditions at the hyperlocal level.
Several forces drive inventory up or down. New construction permits, existing homeowners deciding whether to sell, foreclosure activity, investor purchases, and even demographic shifts all play a role. When mortgage rates rise sharply, many existing homeowners who locked in low rates during previous years choose to stay put, a phenomenon often called the lock-in effect. That reduces inventory, which in turn pushes prices higher even as higher rates cool demand. The result is a market that can feel contradictory: expensive financing and expensive homes at the same time.
The Direct Link Between Inventory and Home Prices
The relationship between inventory and home prices is the most straightforward part of the equation. When supply is low relative to demand, sellers hold the advantage. They can list at aggressive prices, entertain multiple offers, and often waive contingencies because another buyer is waiting in line. In these conditions, home prices rise faster than income growth, and affordability erodes.
When inventory rises, the dynamic flips. Sellers must compete for a smaller pool of qualified buyers. Price cuts become more common, days on market stretch, and negotiation returns to the transaction. This does not mean prices crash overnight. Real estate is famously sticky on the downside because most sellers are not forced to sell. But it does mean that price appreciation slows, stalls, or reverses in the most oversupplied segments.
Consider a practical example. Suppose a metropolitan area has 1,200 active listings and sells 400 homes per month. That is three months of supply, a strong seller's market. If a new employer announces layoffs and 300 additional homes hit the market while sales hold steady, supply jumps to nearly four months. Sellers who need to move quickly will cut prices. Buyers who were previously losing bidding wars suddenly find themselves with options. Prices do not collapse, but the trajectory changes.
For buyers, the lesson is clear: inventory conditions determine how much negotiating room you have. For sellers, inventory tells you whether to price optimistically or realistically. For homeowners who are not transacting, inventory influences their home equity position and long-term wealth. You can track current market conditions and compare personalized offers using tools like the average mortgage rates guide, which puts real-time data in front of you before you make an offer.
How Inventory Indirectly Moves Mortgage Rates
Here is where the relationship gets more nuanced. Mortgage rates are not set by housing inventory directly. They are driven primarily by inflation expectations, Federal Reserve policy, the yield on ten-year Treasury notes, and the secondary mortgage market where loans are packaged and sold to investors. Inventory influences rates through several indirect channels, and understanding those channels helps you anticipate where rates might go.
The first channel is economic growth. A hot housing market with low inventory and rising prices signals strong consumer demand. That demand can feed inflation, and inflation pushes bond yields higher, which drags mortgage rates up. Conversely, a market with bloated inventory and falling prices signals economic weakness, which can push yields lower and mortgage rates down. In this sense, inventory acts as a thermometer for the broader economy.
The second channel is lender risk appetite. When inventory is extremely low and prices are climbing rapidly, lenders worry about appraisals coming in below contract prices. They may tighten underwriting standards or adjust rate sheets to account for the added risk. When inventory is balanced and price growth is stable, lenders tend to be more competitive, which can translate into slightly better rates for qualified borrowers.
The third channel is the composition of sales. Low inventory often means fewer starter homes and more trade-up or luxury transactions. The average loan size rises, and the mix of borrowers shifts. Lenders price for that mix. High inventory often includes more distressed or investor-owned properties, which carry different risk profiles and can influence the average rate quoted in a given market.
None of these channels operates in isolation. A single month of inventory data will not move mortgage rates. But sustained shifts in supply and demand create a feedback loop that eventually shows up in the rate environment. That is why watching inventory trends alongside rate movements gives you a fuller picture than watching either one alone.
Why the Lock-In Effect Changes the Old Rules
Historically, the relationship between mortgage rates and inventory was relatively predictable. When rates rose, demand cooled, inventory built up, and prices softened. When rates fell, demand surged, inventory shrank, and prices climbed. The past few years broke that pattern in a significant way.
Millions of homeowners refinanced when rates were near historic lows. When rates climbed, those homeowners faced a choice: sell and take on a much more expensive mortgage, or stay put and keep their low payment. Most chose to stay. The result was a dramatic reduction in available inventory even as demand remained strong. Prices did not fall as expected because supply dried up faster than demand cooled.
This lock-in effect has important implications for anyone trying to time the market. If you are waiting for rates to drop before buying, understand that lower rates could unleash a wave of sellers who have been waiting on the sidelines. That would increase inventory, which could moderate price growth even as your borrowing costs fall. If you are waiting for prices to drop before buying, understand that inventory would need to rise substantially, and that usually requires either a surge in new construction or a significant economic shock.
For homeowners considering a move, the lock-in effect creates a math problem. Giving up a low rate means your next mortgage costs more per dollar borrowed. You can run the numbers on a refinance or new purchase using a mortgage financing resource that lets you compare scenarios side by side before you decide whether moving makes financial sense.
Regional Variation: Why National Headlines Mislead
National inventory statistics make for clean headlines, but they obscure enormous regional differences. A market like Austin, Texas, which saw a construction boom, may have months of supply that look nothing like a market like Boston, Massachusetts, where geographic constraints limit new building. Similarly, coastal California markets operate under different rules than Midwest markets where land is abundant.
These regional differences mean that the same mortgage rate environment produces different outcomes depending on where you live. In a tight inventory market, a rate increase might barely dent demand because buyers have few alternatives. In a high inventory market, the same rate increase might stall sales entirely because buyers can afford to wait.
For buyers, this means national rate forecasts are only a starting point. What matters is how rates interact with local inventory. A rate that feels high nationally might still be workable in a market where prices are softening. A rate that feels low nationally might not help in a market where bidding wars push final prices far above asking.
For sellers, regional inventory data tells you how much competition you face. If you are listing in a market with two months of supply, you can price aggressively. If you are listing in a market with eight months of supply, you need to price to sell because buyers have options and time.
Key Metrics to Watch in Any Market
Whether you are buying, selling, or simply monitoring your home equity, a handful of metrics will tell you more about market direction than any single headline. Here are the most useful ones to track:
- Months of supply: This is the single best indicator of market balance. Under four months favors sellers. Four to six months is balanced. Over six months favors buyers.
- Days on market: Rising days on market signals cooling demand or growing inventory. Falling days on market signals the opposite.
- Sale-to-list price ratio: When homes sell above asking, inventory is tight. When they sell below asking, inventory is loosening.
- New listings trend: A surge in new listings can signal that sellers are losing confidence or that life events are forcing moves. A decline can signal lock-in or seasonal patterns.
- Price cuts as a percentage of active listings: When more sellers cut prices, the market is shifting in buyers' favor.
These metrics work together. A market with rising inventory, rising days on market, and falling sale-to-list ratios is clearly tilting toward buyers. A market with falling inventory and rising sale-to-list ratios is tilting toward sellers. Watching the trend over several months is more informative than reacting to a single data release.
For mortgage rate watchers, the key is to combine inventory data with rate data. If inventory is rising and rates are falling, buyers gain on both fronts. If inventory is falling and rates are rising, affordability deteriorates quickly. Most markets fall somewhere in between, which is why personalized rate quotes matter more than national averages.
Practical Strategies for Buyers in Low Inventory Markets
Low inventory markets are frustrating, but they are not impossible. The key is to prepare before you shop so that when the right home appears, you can act quickly and credibly.
First, get pre-approved rather than pre-qualified. In a competitive market, sellers want certainty. A pre-approval letter from a lender carries more weight because it means your finances have been reviewed. It also tells you exactly what you can afford, which prevents you from falling in love with a home that is out of reach.
Second, be flexible on terms that do not cost you much. Closing date flexibility, rent-back agreements, and modest appraisal gap coverage can make your offer more attractive without dramatically increasing your financial risk. In a low inventory market, the buyer who makes the process easy for the seller often wins, even if their price is not the highest.
Third, expand your search criteria strategically. If your ideal neighborhood is picked over, look at adjacent neighborhoods, homes that need cosmetic work, or properties that have been on the market longer than average. These opportunities exist in every market, but they require you to look past surface imperfections and focus on location and bones.
Fourth, monitor rates as closely as you monitor listings. A small rate improvement can increase your purchasing power by tens of thousands of dollars. Locking in at the right moment can make the difference between affording the home you want and settling for something less.
What Sellers Should Understand About Inventory
If you are selling, inventory is your competition. Every other listing in your price range and neighborhood is a rival for the same pool of buyers. Understanding how much competition you face should drive your pricing, staging, and marketing decisions.
In a low inventory market, you have leverage. You can price at or slightly above recent comparable sales, limit showings to serious buyers, and hold out for strong offers. But even in a seller's market, overpricing is a mistake. Buyers may be desperate, but they are not irrational. An overpriced home will sit, and sitting inventory becomes stale inventory, which ultimately sells for less.
In a high inventory market, you need to be realistic. Price to the current market, not the market of six months ago. Invest in professional photography and staging. Be flexible on inspection repairs and closing timelines. The sellers who succeed in buyer's markets are the ones who accept reality quickly and adjust accordingly.
For homeowners who are not selling, inventory still matters. Rising inventory can slow your home equity growth or even reduce it. Falling inventory can boost your equity and make a cash-out refinance or home equity line of credit more attractive. Understanding the trend helps you decide when to tap equity and when to wait.
How RateChecker Helps You Navigate Any Inventory Environment
Whether inventory is tight or loose, your mortgage rate is one variable you can actually control by shopping around. RateChecker is built for exactly that purpose. It is a digital platform that provides real-time mortgage rate comparisons, financial tools, and educational resources for home buyers and homeowners. You can compare personalized quotes for home purchase, refinance, home equity loans, and reverse mortgages, all in one place.
The platform is not a lender, mortgage broker, or bank. It does not issue loan offers or approvals, and it does not provide financial, tax, or lending advice. Instead, it connects you with a network of participating lenders who set their own rates and terms. That transparency is the point. You see competing offers side by side, and you decide which one fits your goals.
RateChecker also offers an interactive mortgage calculator that helps you estimate monthly payments based on loan amount, interest rate, and term. If you are trying to figure out how a rate change would affect your budget, that tool gives you a concrete number to work with. The site also publishes consumer-focused financial news, mortgage industry trends, and step-by-step guides that help you understand the mortgage process and compare loan options without jargon.
In a low inventory market, having a pre-approval in hand and knowing your rate gives you a competitive edge. In a high inventory market, comparing rates ensures you are not leaving money on the table when you have more negotiating room on price. Either way, the first step is the same: understand your numbers before you make a move.
Putting It All Together
Housing inventory and mortgage rates are not the same thing, but they are deeply connected through the broader economy and through the behavior of buyers and sellers. Low inventory pushes prices up and can contribute to inflation, which eventually pushes rates higher. High inventory cools prices and can signal economic weakness, which eventually pushes rates lower. The relationship is not instant, and it is not perfectly predictable, but it is real.
For anyone navigating the housing market, the practical takeaway is to watch both variables together. Inventory tells you how much competition you face and how much negotiating power you have. Mortgage rates tell you what financing costs and how much home you can afford. Neither one alone gives you the full picture.
Start by understanding your local inventory conditions using the metrics outlined above. Then compare personalized mortgage rate quotes so you know exactly what you qualify for. RateChecker makes that second step fast and free, and it puts you in a position to act confidently whether the market favors buyers or sellers. The more informed you are, the less likely you are to make an emotional decision in a market that rewards preparation over impulse.